Owners in their sixties and seventies often face the same question in three forms: stay put, move to something smaller, or turn part of the flat into retirement income. Each is a different kind of decision, not just a different price. This guide sets out what HDB's own pages say about the options so you can see what each one changes.
Three routes, side by side
Route | What changes |
|---|---|
Stay as is | Keep: the flat and its remaining lease. Give up: nothing now. Check: the costs of keeping the flat livable as you age. |
Right-size to a smaller flat | Keep: a different flat that better fits your needs. Give up: the current flat, which is sold. Cash from: net sale proceeds, plus Silver Housing Bonus if eligible (up to $40,000). Check: eligibility for the next flat and the bonus conditions. |
Lease Buyback | Keep: a shorter lease you pick (30 or 35 years at age 65 to 69). Give up: the tail-end of the lease, sold to HDB. Cash from: sale of the lease to HDB after the RA is topped up; up to $100,000 cash kept per household. Check: not transferable on the open market; no renting out the whole flat. |
The table is structural. It does not say which route is better, because that depends on your health, your family, how long you expect to live in the flat, and what you need in retirement income.
Route 1: Lease Buyback
Under the Lease Buyback Scheme you sell the tail-end of your flat's lease back to HDB and stay in the flat for the lease you keep. HDB sets out who can apply [1][2]:
- All owners aged 65 or over, with at least one Singapore citizen.
- Gross monthly household income of $16,000 or less.
- All HDB flat types except short-lease flats, HUDC and EC.
- No concurrent private residential property, and at most one non-residential private property.
- A minimum occupation period of five years (ten for Plus and Prime flats).
- At least 20 years of lease left to sell.
The money works through your CPF Retirement Account (RA). You use the proceeds to bring each owner's RA up to a set balance before you can keep cash. HDB's table headings call these figures "top-up requirements", but its footnotes and worked example show they are the balance the RA must reach, so the amount you actually add is that figure minus what is already in your RA [2]. HDB's example for a 65-year-old owner with $20,000 in the RA and a $110,200 target adds $90,200 [2]. We have not checked how HDB treats an RA already above the target, so check that with HDB.
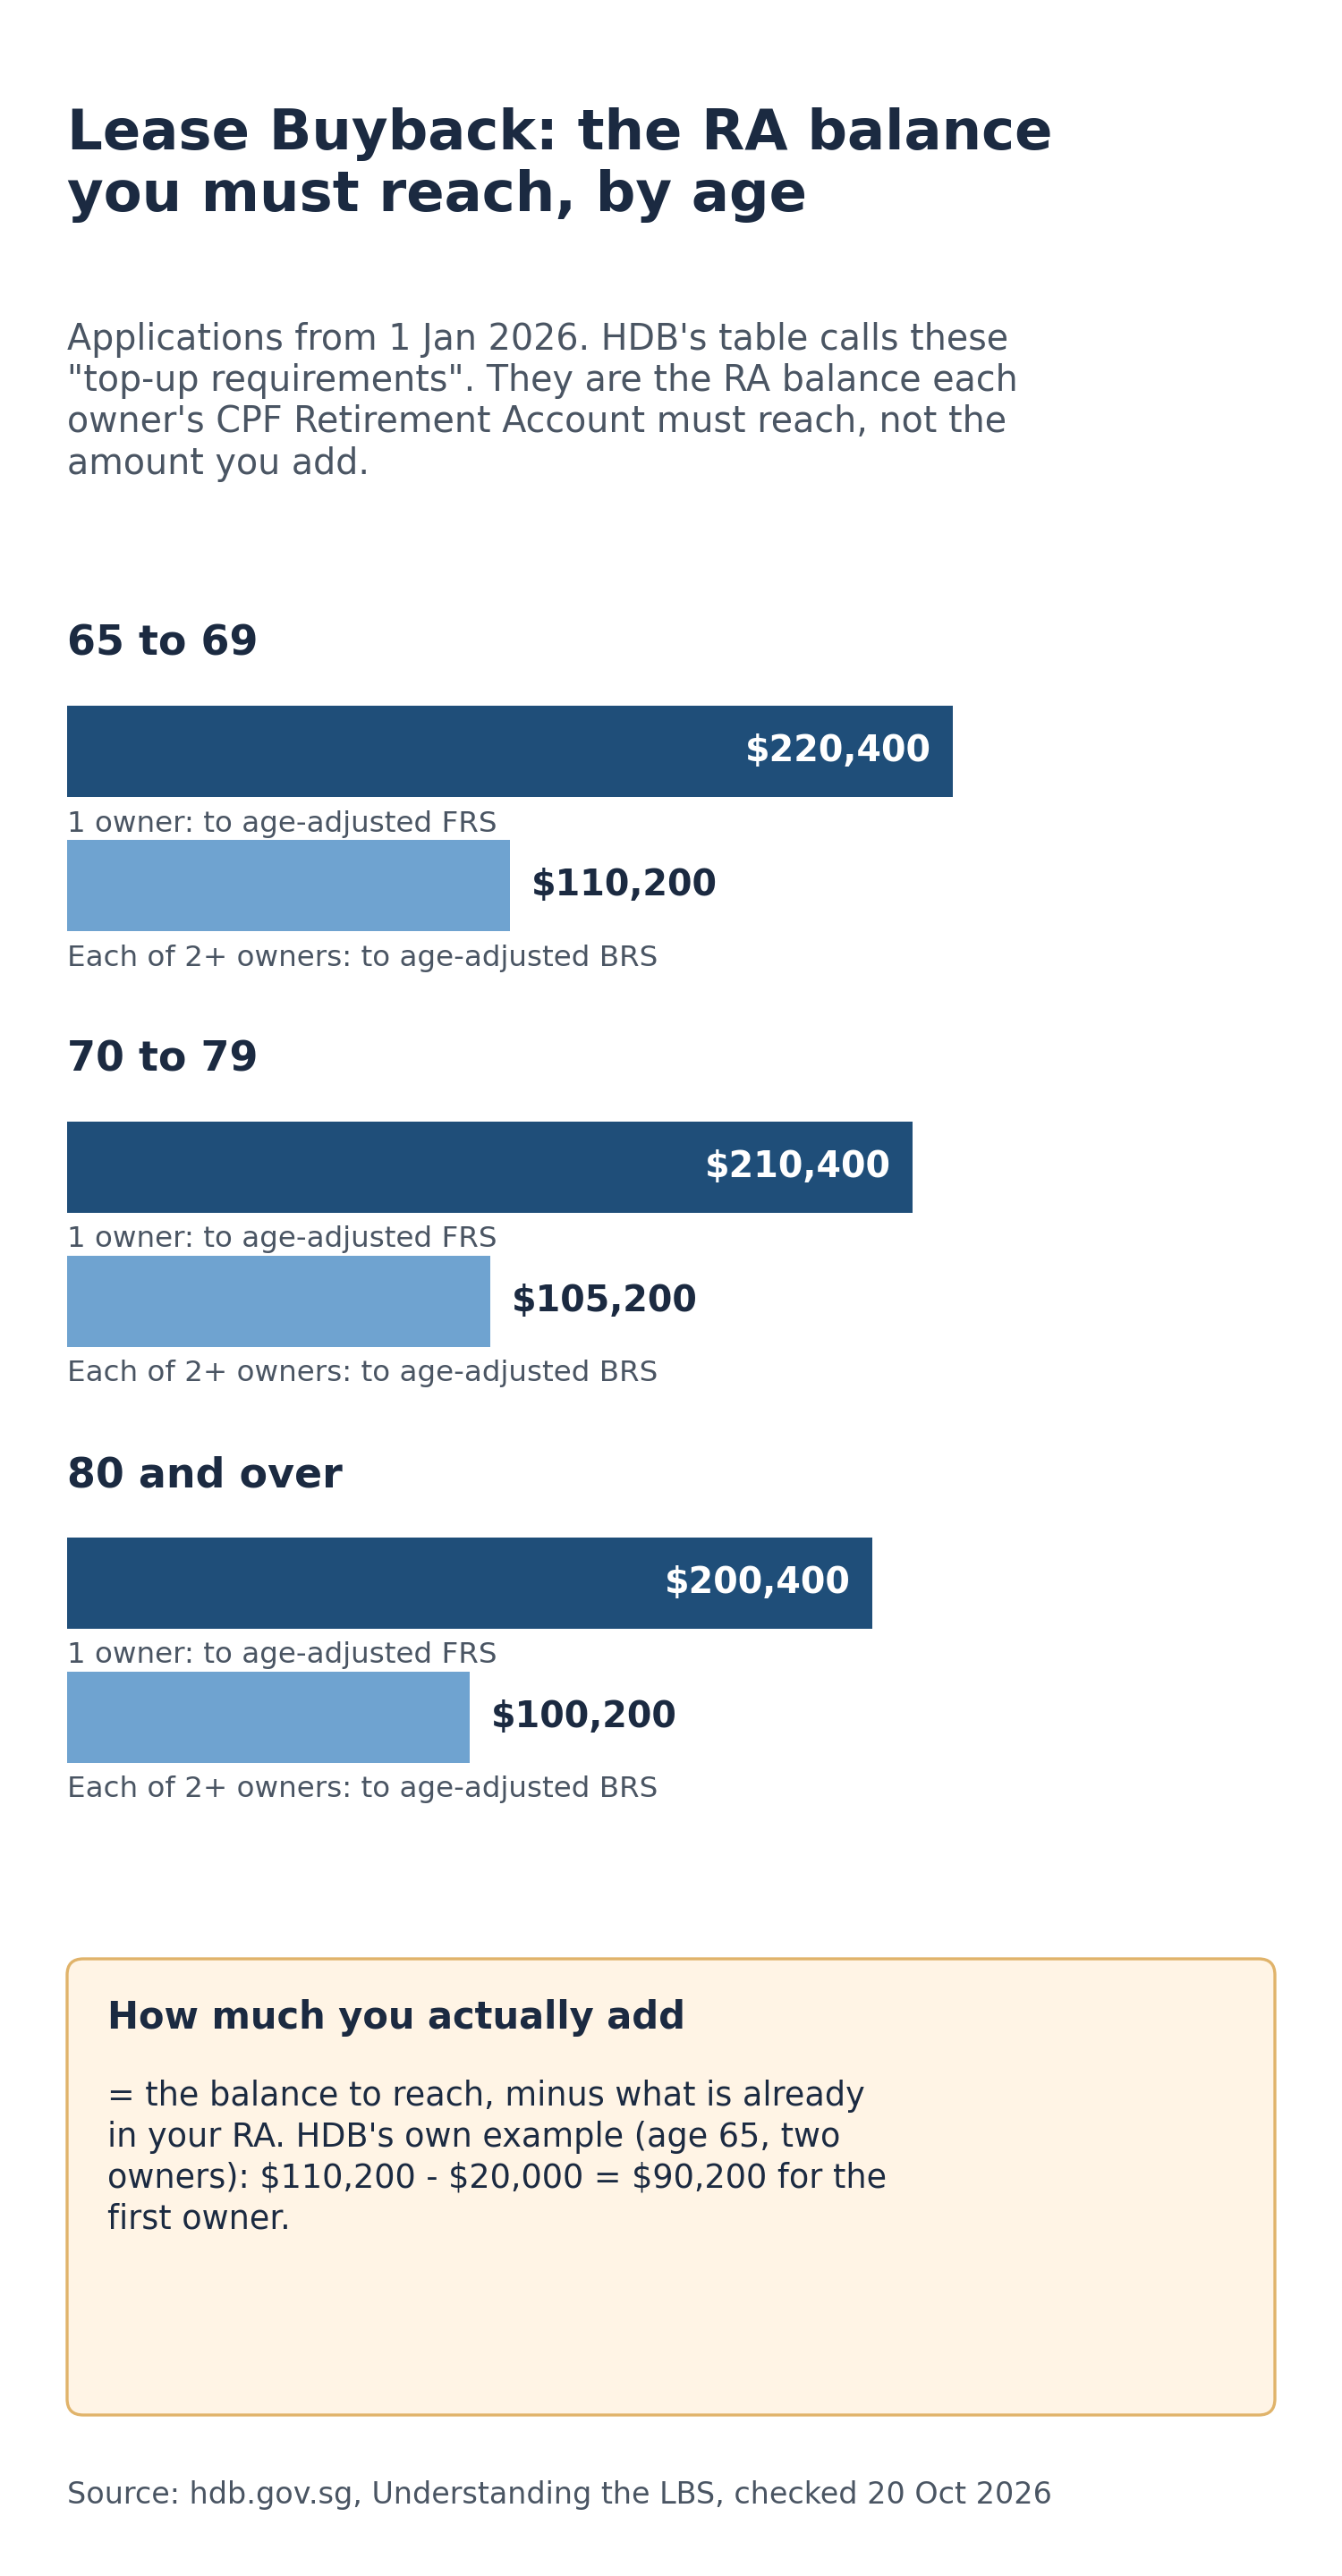
A single owner brings the RA to the age-adjusted Full Retirement Sum. Two or more owners each bring their own RA to the age-adjusted Basic Retirement Sum [2]. After the top-up, you can keep up to $100,000 in cash per household. Anything left over tops up RAs to the FRS before more cash is retained [2]. If your RA has at least $60,000 after the top-up, it buys CPF LIFE, which is not available from age 80 [2].
The lease you keep depends on the age of the youngest owner [2]:
Age of youngest owner | Minimum lease to keep | Options (years) |
|---|---|---|
65 to 69 | 30 | 30, 35 |
70 to 74 | 25 | 25, 30, 35 |
75 to 79 | 20 | 20, 25, 30, 35 |
80 and over | 15 | 15, 20, 25, 30, 35 |
The Lease Buyback Bonus is up to $30,000 for a 3-room or smaller flat, $15,000 for a 4-room and $7,500 for a 5-room or larger. The full bonus needs a total RA top-up of $60,000 or more, and is pro-rated below that. There is no bonus if all owners have already reached the FRS [2].
Terms that matter in practice [2]:
- A Lease Buyback flat cannot be sold on the open market, and the whole flat cannot be rented out.
- Ending the arrangement early refunds the remaining lease pro-rated on a straight-line basis, and CPF LIFE payouts continue.
- If you outlive the lease you keep, HDB works out housing based on your circumstances.
- When an owner dies, a spouse or child living there may stay or return the flat.
HDB's own worked example, shown as an infographic on the same page, uses a couple aged 65, joint owners of a fully paid 4-room flat worth $450,000 with 65 years of lease left, with RA balances of $20,000 and $20,400. They keep 30 years and sell the tail-end 35 years to HDB for $190,000, so each owner receives $95,000 [2].
Step in HDB's example | Result |
|---|---|
Proceeds to each owner | $95,000 |
Each owner's RA is brought to the Basic Retirement Sum | $110,200 (at age 65) |
Cash left over for the couple | $10,000 |
Lease Buyback bonus (RA top-up above $60,000, 4-room flat) | $15,000 |
CPF LIFE payout | $1,240 a month for life, based on a $180,000 top-up to the couple's RA and their RA balances |
These are HDB's illustrative assumptions, not a quote for any flat. The infographic does not say what the couple's own retirement income needs are, and it shows only one household.
Route 2: Right-size to a smaller flat
Selling and buying a smaller home changes the flat, not just the cash. Two HDB schemes are designed with older owners in mind.
Silver Housing Bonus
From 1 December 2025 the Silver Housing Bonus is up to $40,000 per household [3]. HDB's conditions include [3]:
- At least one Singapore citizen aged 55 or over, with household income of $16,000 or less.
- You sell an existing HDB flat, or a private residence with an annual value up to $31,000, and the next home is a 3-room (excluding terrace) or 2-room-or-smaller flat, including Community Care Apartments.
- Net sale proceeds must be positive, and you commit to a net RA increase of up to $60,000 (capped by the FRS), which may come from CPF housing refunds.
- Timing: before the sale, or within 12 months of completing the sale of the existing property. Apply within one year of completing the second transaction.
The bonus is $30,000 at the full $60,000 commitment, pro-rated at $1 per $2 committed, plus an extra $10,000 for a 2-room-or-smaller flat or a Community Care Apartment. A private property with an annual value of $21,000 to $31,000 gets up to $10,000 (pro-rated $1 per $6), plus the extra $10,000, so $20,000 at most [3].
Short-lease 2-room Flexi and Community Care Apartments
The short-lease 2-room Flexi flat is meant for seniors. It cannot be sold on the open market: it is returned to HDB, which pays the unused lease value. Costs on HDB's page include a $10 application fee, a $500 booking fee and a 10% downpayment at the Agreement for Lease, with the Deferred Downpayment Scheme possible for existing owners [4].
Community Care Apartments have a senior-friendly design and a mandatory Basic Service Package (24-hour emergency response, simple home fixes, and arranging add-on care), operated by Vanguard Healthcare. Optional services cost extra, and subsidies are means-tested for people who need permanent ADL assistance [5]. Leases run 15 to 45 years in five-year steps for the November 2026 BTO exercise (15 to 35 for earlier ones) and must cover the applicant and spouse to age 95. The flat price is paid upfront in cash and/or CPF, and a current HDB flat or private property must be disposed of within six months of key collection [5]. HDB notes it is not suitable for people with high medical or nursing care needs [5].
Route 3: Stay as you are
Staying is the one option with no scheme attached, which makes it easy to overlook. The practical questions are about the flat, not the paperwork: can you manage the stairs, the bathroom and the neighbourhood in ten years? HDB's EASE programme subsidises items such as grab bars that improve mobility and safety in the flat, and is offered as part of the Home Improvement Programme or by direct application [6]. We did not price EASE or other upkeep costs in this guide, because the eligible items and subsidies depend on your block and household. Check the HDB page.
What we could not verify
This guide does not compare three households side by side. The only household example is HDB's own Lease Buyback case. We did not model any household's cash flow, and we did not read a reader or practitioner report on any of these routes, so there are no lived-experience quotes here. The HDB pages describe rules, not how long approvals take or how people feel about the trade-offs.
Questions to answer before you choose
- How many years do I realistically expect to stay in this flat, and who might live there after me?
- If I keep a shorter lease, what is my plan if I live past it?
- How much would I add to my RA (the target minus what is already there), and what would I really keep in cash?
- If I right-size, is the next flat's lease, size and service package one I can live with at 80?
- Do I meet each scheme's household income, property and occupation conditions today, and would that change?
References
- HDB, Lease Buyback Scheme. https://www.hdb.gov.sg/managing-my-home/retirement-planning/monetising-flat-for-retirement/lease-buyback-scheme-lbs ↩
- HDB, Understanding the Lease Buyback Scheme. https://www.hdb.gov.sg/managing-my-home/retirement-planning/monetising-flat-for-retirement/lease-buyback-scheme-lbs/understanding-the-lbs ↩ ↩ ↩ ↩ ↩ ↩ ↩ ↩ ↩ ↩
- HDB, Silver Housing Bonus. https://www.hdb.gov.sg/managing-my-home/retirement-planning/monetising-flat-for-retirement/silver-housing-bonus ↩ ↩ ↩
- HDB, Short-lease 2-room Flexi flat. https://www.hdb.gov.sg/buying-a-flat/bto-sbf-and-open-booking-of-flats/finding-a-new-flat/types-of-flats/short-lease-2-room-flexi-flat ↩
- HDB, Community Care Apartments. https://www.hdb.gov.sg/buying-a-flat/bto-sbf-and-open-booking-of-flats/finding-a-new-flat/types-of-flats/community-care-apartments ↩ ↩ ↩
- HDB, Enhancement for Active Seniors (EASE). https://www.hdb.gov.sg/residential/living-in-an-hdb-flat/for-our-seniors/ease ↩